1 defined-risk option setups lead the Aug 20, 2026 board
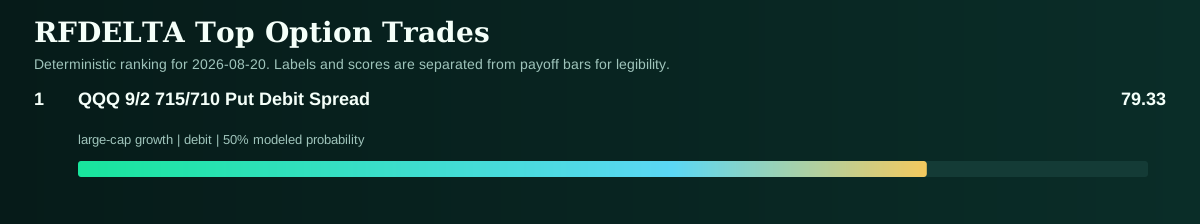
QQQ 9/2 715/710 Put Debit Spread ranks first with a 79.33 score, 49.7% modeled probability of profit and $219.00 maximum one-lot risk. The basket balances 0 bullish and 1 bearish expression.
The option board is not rewarding indiscriminate beta. Across the published names, the mean five-session move is -2.7%, while 0 setups carry realized volatility above 65%. That combination favors defined-risk structures and hard entry limits over naked premium exposure.
The screen quotes 105 liquid underlyings and requests 40 option chains through its core, mover, volume and rotation sleeves. It accepts only same-session chains with two usable legs, then forces every idea through the same conservative mark: pay the ask for the long option and receive the bid for the short. The resulting ranking is intentionally harsher than a midpoint screen, because a trade that only works at a theoretical fill is not a durable public idea.
Direction comes from five- and twenty-session price structure rather than a headline guess. That keeps the daily board responsive to what is actually trading while the scenario engine still reserves room for jumps, volatility expansion and path-dependent failure. The result is a short list, not a promise that every liquid ticker deserves a trade.
Top score79.33
Avg. probability49.7%
Basket max risk$219
Data as ofAug 20, 11:18 AM EDT
Ranked opportunity set
What leads the board
Every score combines four payoff views, conservative expected value, liquidity, session follow-through and multi-session alignment.
1. QQQ put debit79.33
QQQ 9/2 715/710 Put Debit Spread
Payoff discipline
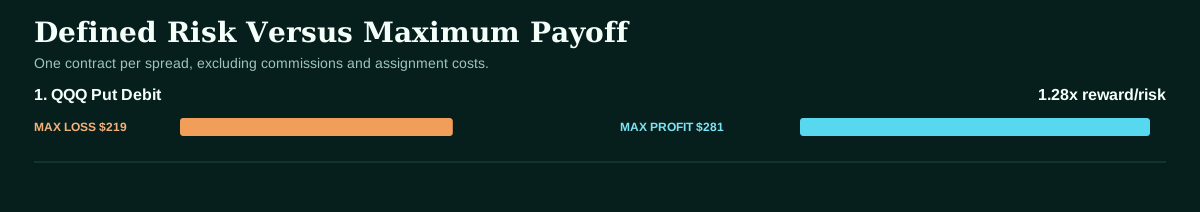
Risk is known before the trade
Maximum loss and maximum profit are shown for one vertical spread using conservative entry prices.
1. QQQ put debit1.28x
Max loss $219
Max profit $281
Detailed trade intelligence
Trade 1
1
Highest-conviction screen | large-cap growth
QQQ 9/2 715/710 Put Debit Spread
RFDELTA score79.33
Debit entry2.19
Prob. profit49.7%
Max loss$219.00
Max profit$281.00
Breakeven$712.81
Reward / risk1.28x
Why it ranks
The setup scores 79.33 on the common scale. Four-model consensus places probability of profit at 49.7%, 5.9% above the payoff hurdle, with 0.83 liquidity quality and positive modeled expectancy of $23.51.
QQQ enters with -2.7% five-session momentum and +2.9% over twenty sessions. Realized volatility is 22.7%, placing the underlying in a mean reversion regime. The bearish structure expresses that tape without allowing the loss to expand beyond the spread debit or defined credit width.
Trade construction
Buy the 715 put and sell the 710 put, both expiring Sep 2, 2026. The debit mark of 2.19 assumes the long ask and short bid, not a midpoint. Do not pay more than 2.19 for the spread without rerunning the payoff.
Maximum one-lot profit is $281.00, or 1.28 times maximum risk. The simulation assigns 45.6% probability to finishing near maximum profit and uses 19.5% implied volatility across deterministic jump-stress paths.
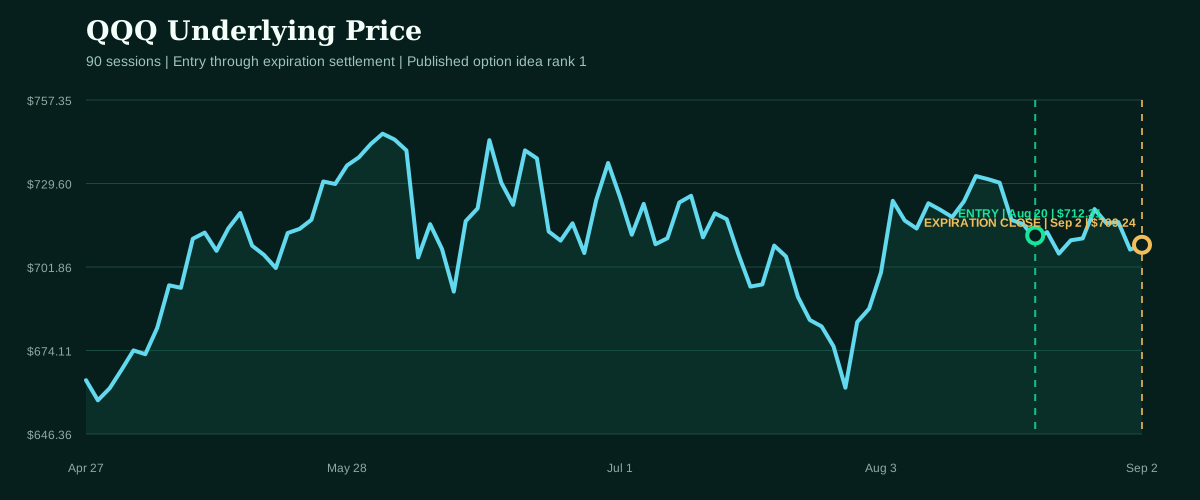
Underlying entry $712.31 on Aug 20, 2026; expiration close $709.24 on Sep 2, 2026.
History260 sessions
RSI (14)63.3
MACD spread+0.09%
ATR (14)1.5%
Realized vol.22.7%
ATM implied vol.19.4%
Expected move2.9%
Risk read
Maximum one-lot loss is $219.00. Breakeven is $712.81 and sits 0.1% above the source mark, providing an upside cushion. Primary watch: a directional break before expiration. A break in the stated directional regime invalidates the reason for holding even when the contractual maximum loss remains unchanged.
Completed basket review
Aug 20, 2026 basket closes with $281.00 final P/L
The 1-trade basket finished with 1 win, 0 near-breakeven results and 0 losses. The modeled one-lot portfolio produced a gain of $281.00, equal to +128.3% of the maximum capital at risk.
QQQ 9/2 715/710 Put Debit Spread was the strongest contributor at $281.00.
What worked: put debit.
1 wins0 near breakeven0 losses$281 final P/L
QQQ 9/2 715/710 Put Debit Spreadwin
QQQ closed at $709.24 for expiration settlement, producing $281.00 on the one-lot spread.
$281
Accountability ledger
Every prior basket, one expanding record
Open positions remain visible beside completed baskets, preserving the original trade terms and the final modeled expiration result for each published day.
August 10, 2026Daily market editionopen0 resolved / 1 open$0
The Aug 10, 2026 basket has no scored expiration result yet. 1 position remains open.
0 wins0 near breakeven0 losses1 still open
NFLX 8/21 76/79 Call Debit Spreadopen
The spread remains open through Aug 21, 2026; no expiration result is assigned.
Open
July 31, 2026Daily market editioncomplete1 resolved / 0 open-$115
The Jul 31, 2026 basket has 0 wins, 0 near-breakeven results and 1 loss across 1 resolved spread, for modeled one-lot expiration P/L of -$115.00. All listed positions are resolved.
0 wins0 near breakeven1 losses0 still open
NFLX 8/14 71/67 Put Debit Spreadloss
NFLX closed at $78.16 for expiration settlement, producing -$115.00 on the one-lot spread.
-$115
July 29, 2026Daily market editioncomplete1 resolved / 0 open-$204
The Jul 29, 2026 basket has 0 wins, 0 near-breakeven results and 1 loss across 1 resolved spread, for modeled one-lot expiration P/L of -$204.00. All listed positions are resolved.
0 wins0 near breakeven1 losses0 still open
SPY 8/11 735/730 Put Debit Spreadloss
SPY closed at $770.56 for expiration settlement, producing -$204.00 on the one-lot spread.
-$204
July 21, 2026Daily market editioncomplete1 resolved / 0 open$59
The Jul 21, 2026 basket has 1 win, 0 near-breakeven results and 0 losses across 1 resolved spread, for modeled one-lot expiration P/L of $59.00. All listed positions are resolved.
1 wins0 near breakeven0 losses0 still open
TLT 8/3 83/84 Call Credit Spreadwin
TLT closed at $82.19 for expiration settlement, producing $59.00 on the one-lot spread.
$59
July 17, 2026Daily market editioncomplete1 resolved / 0 open$256
The Jul 17, 2026 basket has 1 win, 0 near-breakeven results and 0 losses across 1 resolved spread, for modeled one-lot expiration P/L of $256.00. All listed positions are resolved.
1 wins0 near breakeven0 losses0 still open
QQQ 7/30 700/705 Call Credit Spreadwin
QQQ closed at $683.55 for expiration settlement, producing $256.00 on the one-lot spread.
$256
July 16, 2026Daily market editioncomplete2 resolved / 0 open$262
The Jul 16, 2026 basket has 2 wins, 0 near-breakeven results and 0 losses across 2 resolved spreads, for modeled one-lot expiration P/L of $262.00. All listed positions are resolved.
2 wins0 near breakeven0 losses0 still open
TLT 7/29 80.5/84 Call Credit Spreadwin
TLT closed at $82.85 for expiration settlement, producing $70.00 on the one-lot spread.
$70
IWM 7/29 292/295 Call Credit Spreadwin
IWM closed at $288.57 for expiration settlement, producing $192.00 on the one-lot spread.
$192
July 14, 2026Daily market editioncomplete5 resolved / 0 open-$8
The Jul 14, 2026 basket has 2 wins, 0 near-breakeven results and 3 losses across 5 resolved spreads, for modeled one-lot expiration P/L of -$8.00. All listed positions are resolved.
2 wins0 near breakeven3 losses0 still open
TLT 7/27 84/82 Put Debit Spreadloss
TLT closed at $83.75 for expiration settlement, producing -$18.00 on the one-lot spread.
-$18
BAC 7/31 60/59 Put Credit Spreadwin
BAC closed at $61.95 for expiration settlement, producing $27.00 on the one-lot spread.
$27
C 7/31 140/142 Call Credit Spreadwin
C closed at $132.45 for expiration settlement, producing $42.00 on the one-lot spread.
$42
T 7/31 21/20 Put Debit Spreadloss
T closed at $23.25 for expiration settlement, producing -$32.00 on the one-lot spread.
-$32
F 7/31 14/13.5 Put Debit Spreadloss
F closed at $14.68 for expiration settlement, producing -$27.00 on the one-lot spread.
-$27
July 13, 2026Daily market editioncomplete5 resolved / 0 open$645
The Jul 13, 2026 basket has 4 wins, 0 near-breakeven results and 1 loss across 5 resolved spreads, for modeled one-lot expiration P/L of $645.00. All listed positions are resolved.
4 wins0 near breakeven1 losses0 still open
BAC 7/24 59/58 Put Credit Spreadwin
BAC closed at $62.05 for expiration settlement, producing $39.00 on the one-lot spread.
$39
NKE 7/24 43/42 Put Credit Spreadloss
NKE closed at $41.70 for expiration settlement, producing -$77.00 on the one-lot spread.
-$77
ORCL 7/24 145/148 Call Credit Spreadwin
ORCL closed at $114.99 for expiration settlement, producing $60.00 on the one-lot spread.
$60
QQQ 7/24 715/708 Put Debit Spreadwin
QQQ closed at $684.23 for expiration settlement, producing $452.00 on the one-lot spread.
$452
IWM 7/24 294/291 Put Debit Spreadwin
IWM closed at $291.17 for expiration settlement, producing $171.00 on the one-lot spread.
$171
Daily Market Read
The board is selling optimism, but only with defined risk
Today's 1-spread board is defensively tilted: 0 bullish and 1 bearish expressions, 49.7% average modeled probability of profit and $219 of aggregate one-lot maximum risk. Across 5 retained market boards, directional balance has moved more defensive; the top score is +79.33 points versus the prior-board average and modeled win probability is +49.7 percentage points.
The market can look calm at index level while the option chain tells a less comfortable story. The published names carry -2.7% average five-session momentum and cluster most heavily in a mean reversion regime. That is not a blanket vote on the market; it is a warning that the day's best-defined payoffs are selective rather than broad.
No current leader repeats from the available prior boards. Rotation is doing more work than durable leadership, and that is usually where chasing yesterday's winner becomes expensive. The top score sits at 79.33, while the basket's expected value totals $24 under conservative bid-and-ask entries. A ranking that cannot absorb the spread between theory and execution does not belong on the public board.
Average implied and realized volatility are close at 19.5% and 22.7%. With little volatility cushion either way, strike placement and entry discipline matter more than a broad volatility call. The structure mix is 0 credit and 1 debit spreads, so the board is neither blindly buying convexity nor mechanically selling premium. It is paying only where direction can justify the bill and collecting only where the strikes leave room for error.
The public headline radar is concentrated in rates. That is the catalyst layer, not the trade instruction: the useful question is whether those stories confirm the board's mean reversion regime or merely create an opening burst that fades after liquidity arrives.
What to watch
Breadth confirmation0 bullish / 1 bearish; -2.7% mean five-session move
Defensive skew needs downside follow-through. A fast reversal above entry regimes would invalidate the premise before contractual risk is reached.
Volatility spread19.5% implied vs 22.7% realized
Watch whether implied volatility expands with price movement or collapses after the opening catalyst. That relationship decides whether direction alone is enough.
Leadership durabilityNo repeat leader in the current board
Rapid rotation argues for smaller assumptions and harder entry limits. New leadership has not yet earned persistence.
News catalyst1 ranked headlines across 1 themes
The leading rates headlines matter only where they alter cash-flow expectations, funding costs or volatility. Price confirmation decides whether the story belongs in the trade.
Risk budget$219 maximum one-lot basket loss (+$219 vs prior average)
Maximum losses are additive. Correlated names can fail together even when each spread is individually defined, so basket risk matters more than the comfort of any single cap.
Rolling comparison uses 5 retained published market sessions: Aug 20, 2026, Aug 19, 2026, Aug 18, 2026, Aug 17, 2026, Aug 14, 2026. The current screen ranked 18 candidates across 40 included symbols. Headline ranking uses publication time, market relevance, source quality, symbol relevance and topic diversity. Market evidence is timestamped Aug 20, 2026, 11:18 AM EDT. RFDELTA Top Option Trades is market intelligence, not individualized investment advice. Options can expire worthless, spreads can be assigned early, and displayed quotes may move before an order can be filled.
Why it ranks
The setup scores 79.33 on the common scale. Four-model consensus places probability of profit at 49.7%, 5.9% above the payoff hurdle, with 0.83 liquidity quality and positive modeled expectancy of $23.51.
QQQ enters with -2.7% five-session momentum and +2.9% over twenty sessions. Realized volatility is 22.7%, placing the underlying in a mean reversion regime. The bearish structure expresses that tape without allowing the loss to expand beyond the spread debit or defined credit width.
Trade construction
Buy the 715 put and sell the 710 put, both expiring Sep 2, 2026. The debit mark of 2.19 assumes the long ask and short bid, not a midpoint. Do not pay more than 2.19 for the spread without rerunning the payoff.
Maximum one-lot profit is $281.00, or 1.28 times maximum risk. The simulation assigns 45.6% probability to finishing near maximum profit and uses 19.5% implied volatility across deterministic jump-stress paths.