2 defined-risk option setups lead the Sep 28, 2026 board
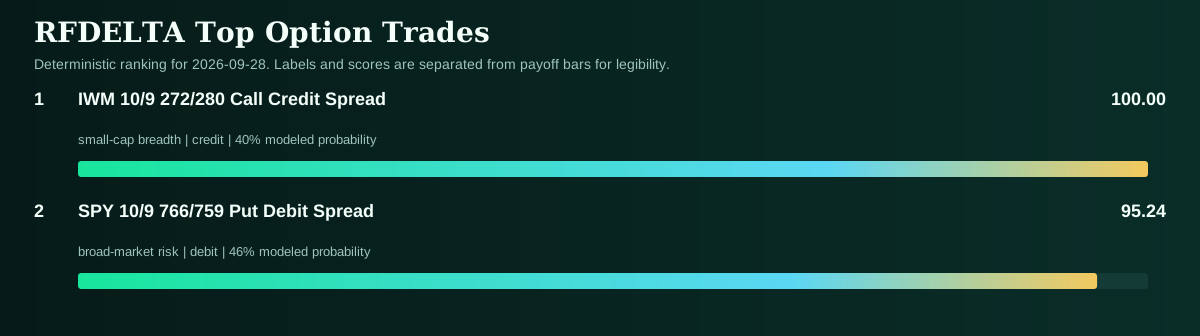
IWM 10/9 272/280 Call Credit Spread ranks first with a 100.00 score, 39.8% modeled probability of profit and $237.00 maximum one-lot risk. The basket balances 0 bullish and 2 bearish expressions.
The option board is not rewarding indiscriminate beta. Across the published names, the mean five-session move is -1.5%, while 0 setups carry realized volatility above 65%. That combination favors defined-risk structures and hard entry limits over naked premium exposure.
The screen quotes 105 liquid underlyings and requests 40 option chains through its core, mover, volume and rotation sleeves. It accepts only same-session chains with two usable legs, then forces every idea through the same conservative mark: pay the ask for the long option and receive the bid for the short. The resulting ranking is intentionally harsher than a midpoint screen, because a trade that only works at a theoretical fill is not a durable public idea.
Direction comes from five- and twenty-session price structure rather than a headline guess. That keeps the daily board responsive to what is actually trading while the scenario engine still reserves room for jumps, volatility expansion and path-dependent failure. The result is a short list, not a promise that every liquid ticker deserves a trade.
Top score100.00
Avg. probability42.9%
Basket max risk$484
Data as ofSep 28, 4:50 PM EDT
Ranked opportunity set
What leads the board
Every score combines four payoff views, conservative expected value, liquidity, session follow-through and multi-session alignment.
1. IWM call credit100.00
IWM 10/9 272/280 Call Credit Spread
2. SPY put debit95.24
SPY 10/9 766/759 Put Debit Spread
Payoff discipline
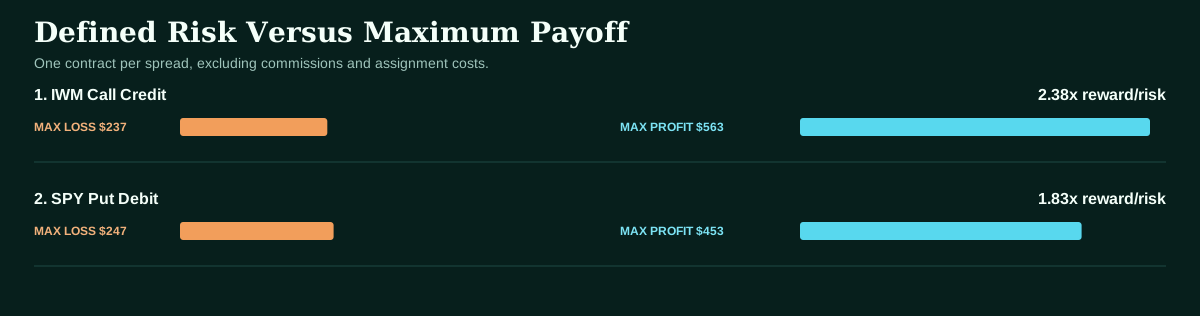
Risk is known before the trade
Maximum loss and maximum profit are shown for one vertical spread using conservative entry prices.
1. IWM call credit2.38x
Max loss $237
Max profit $563
2. SPY put debit1.83x
Max loss $247
Max profit $453
Detailed trade intelligence
Trades 1-2
1
Highest-conviction screen | small-cap breadth
IWM 10/9 272/280 Call Credit Spread
RFDELTA score100.00
Credit entry5.63
Prob. profit39.8%
Max loss$237.00
Max profit$563.00
Breakeven$277.63
Reward / risk2.38x
Why it ranks
The setup scores 100.00 on the common scale. Four-model consensus places probability of profit at 39.8%, 10.1% above the payoff hurdle, with 0.89 liquidity quality and positive modeled expectancy of $71.20.
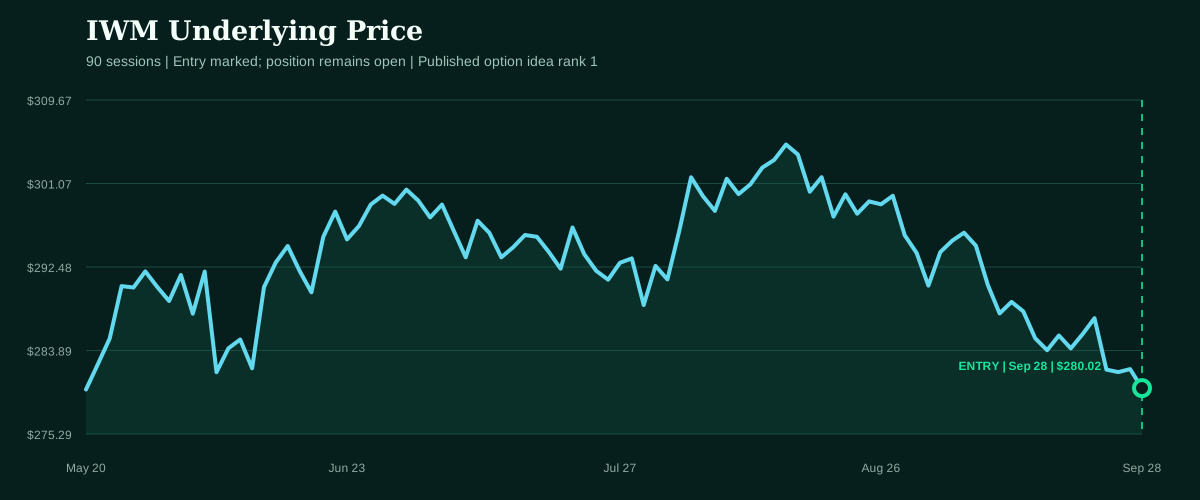
IWM enters with -1.9% five-session momentum and -5.3% over twenty sessions. Realized volatility is 12.3%, placing the underlying in a risk off regime. The bearish structure expresses that tape without allowing the loss to expand beyond the spread debit or defined credit width.
Trade construction
Buy the 280 call and sell the 272 call, both expiring Oct 9, 2026. The credit mark of 5.63 assumes the long ask and short bid, not a midpoint. Do not accept less than 5.63 of credit without rerunning the payoff.
Maximum one-lot profit is $563.00, or 2.38 times maximum risk. The simulation assigns 20.8% probability to finishing near maximum profit and uses 20.6% implied volatility across deterministic jump-stress paths.
Underlying entry $280.02 on Sep 28, 2026; official closes will extend the chart after each session.
History260 sessions
RSI (14)22.8
MACD spread-0.21%
ATR (14)1.3%
Realized vol.12.3%
ATM implied vol.19.2%
Expected move2.7%
Risk read
Maximum one-lot loss is $237.00. Breakeven is $277.63 and requires a 0.8% decline from the source mark. Primary watch: low credit probability; call short strike at/below spot. A break in the stated directional regime invalidates the reason for holding even when the contractual maximum loss remains unchanged.
2
Highest-conviction screen | broad-market risk
SPY 10/9 766/759 Put Debit Spread
RFDELTA score95.24
Debit entry2.47
Prob. profit46.1%
Max loss$247.00
Max profit$453.00
Breakeven$763.53
Reward / risk1.83x
Why it ranks
The setup scores 95.24 on the common scale. Four-model consensus places probability of profit at 46.1%, 10.8% above the payoff hurdle, with 0.92 liquidity quality and positive modeled expectancy of $66.78.
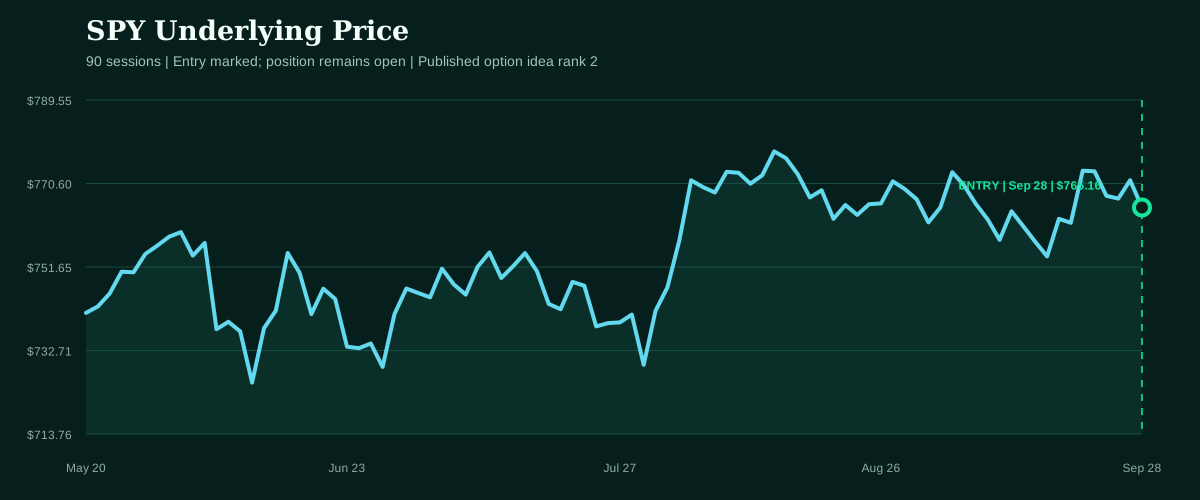
SPY enters with -1.1% five-session momentum and -0.5% over twenty sessions. Realized volatility is 11.1%, placing the underlying in a mixed regime. The bearish structure expresses that tape without allowing the loss to expand beyond the spread debit or defined credit width.
Trade construction
Buy the 766 put and sell the 759 put, both expiring Oct 9, 2026. The debit mark of 2.47 assumes the long ask and short bid, not a midpoint. Do not pay more than 2.47 for the spread without rerunning the payoff.
Maximum one-lot profit is $453.00, or 1.83 times maximum risk. The simulation assigns 38.7% probability to finishing near maximum profit and uses 18.0% implied volatility across deterministic jump-stress paths.
Underlying entry $765.16 on Sep 28, 2026; official closes will extend the chart after each session.
History260 sessions
RSI (14)49.4
MACD spread+0.04%
ATR (14)0.9%
Realized vol.11.1%
ATM implied vol.12.7%
Expected move1.8%
Risk read
Maximum one-lot loss is $247.00. Breakeven is $763.53 and requires a 0.2% decline from the source mark. Primary watch: a directional break before expiration. A break in the stated directional regime invalidates the reason for holding even when the contractual maximum loss remains unchanged.
Accountability ledger
Every prior basket, one expanding record
Open positions remain visible beside completed baskets, preserving the original trade terms and the final modeled expiration result for each published day.
September 18, 2026Daily market editionopen0 resolved / 2 open$0
The Sep 18, 2026 basket has no scored expiration result yet. 2 positions remain open.
0 wins0 near breakeven0 losses2 still open
SPY 10/1 760/755 Put Debit Spreadopen
The spread remains open through Oct 1, 2026; no expiration result is assigned.
Open
TLT 10/2 80/80.5 Call Credit Spreadopen
The spread remains open through Oct 2, 2026; no expiration result is assigned.
Open
September 17, 2026Daily market editionopen0 resolved / 1 open$0
The Sep 17, 2026 basket has no scored expiration result yet. 1 position remains open.
0 wins0 near breakeven0 losses1 still open
SLV 9/30 59/62 Call Debit Spreadopen
The spread remains open through Sep 30, 2026; no expiration result is assigned.
Open
September 10, 2026Daily market editioncomplete2 resolved / 0 open-$66
The Sep 10, 2026 basket has 1 win, 0 near-breakeven results and 1 loss across 2 resolved spreads, for modeled one-lot expiration P/L of -$66.00. All listed positions are resolved.
1 wins0 near breakeven1 losses0 still open
SPY 9/23 755/750 Put Debit Spreadloss
SPY closed at $767.81 for expiration settlement, producing -$162.00 on the one-lot spread.
-$162
IWM 9/23 284/280 Put Debit Spreadwin
IWM closed at $281.92 for expiration settlement, producing $96.00 on the one-lot spread.
$96
August 28, 2026Daily market editioncomplete1 resolved / 0 open$405
The Aug 28, 2026 basket has 1 win, 0 near-breakeven results and 0 losses across 1 resolved spread, for modeled one-lot expiration P/L of $405.00. All listed positions are resolved.
1 wins0 near breakeven0 losses0 still open
IWM 9/11 290/296 Call Credit Spreadwin
IWM closed at $288.89 for expiration settlement, producing $405.00 on the one-lot spread.
$405
August 21, 2026Daily market editioncomplete1 resolved / 0 open-$36
The Aug 21, 2026 basket has 0 wins, 0 near-breakeven results and 1 loss across 1 resolved spread, for modeled one-lot expiration P/L of -$36.00. All listed positions are resolved.
0 wins0 near breakeven1 losses0 still open
TLT 9/4 81/82 Call Credit Spreadloss
TLT closed at $82.21 for expiration settlement, producing -$36.00 on the one-lot spread.
-$36
August 20, 2026Daily market editioncomplete1 resolved / 0 open$281
The Aug 20, 2026 basket has 1 win, 0 near-breakeven results and 0 losses across 1 resolved spread, for modeled one-lot expiration P/L of $281.00. All listed positions are resolved.
1 wins0 near breakeven0 losses0 still open
QQQ 9/2 715/710 Put Debit Spreadwin
QQQ closed at $709.24 for expiration settlement, producing $281.00 on the one-lot spread.
$281
August 10, 2026Daily market editioncomplete1 resolved / 0 open$216
The Aug 10, 2026 basket has 1 win, 0 near-breakeven results and 0 losses across 1 resolved spread, for modeled one-lot expiration P/L of $216.00. All listed positions are resolved.
1 wins0 near breakeven0 losses0 still open
NFLX 8/21 76/79 Call Debit Spreadwin
NFLX closed at $79.59 for expiration settlement, producing $216.00 on the one-lot spread.
$216
July 31, 2026Daily market editioncomplete1 resolved / 0 open-$115
The Jul 31, 2026 basket has 0 wins, 0 near-breakeven results and 1 loss across 1 resolved spread, for modeled one-lot expiration P/L of -$115.00. All listed positions are resolved.
0 wins0 near breakeven1 losses0 still open
NFLX 8/14 71/67 Put Debit Spreadloss
NFLX closed at $78.16 for expiration settlement, producing -$115.00 on the one-lot spread.
-$115
Daily Market Read
The board is selling optimism, but only with defined risk
Today's 2-spread board is defensively tilted: 0 bullish and 2 bearish expressions, 42.9% average modeled probability of profit and $484 of aggregate one-lot maximum risk. Across 5 retained market boards, directional balance has moved more defensive; the top score is +75.99 points versus the prior-board average and modeled win probability is +32.5 percentage points.
The market can look calm at index level while the option chain tells a less comfortable story. The published names carry -1.5% average five-session momentum and cluster most heavily in a mixed regime. That is not a blanket vote on the market; it is a warning that the day's best-defined payoffs are selective rather than broad.
SPY returns to the leading group, which makes follow-through more important than another round of headline enthusiasm. The top score sits at 100.00, while the basket's expected value totals $138 under conservative bid-and-ask entries. A ranking that cannot absorb the spread between theory and execution does not belong on the public board.
Average implied volatility is 19.3% against 11.7% realized volatility. The premium is visible, but expensive options are not automatically good shorts; the spread still has to survive direction and path. The structure mix is 1 credit and 1 debit spreads, so the board is neither blindly buying convexity nor mechanically selling premium. It is paying only where direction can justify the bill and collecting only where the strikes leave room for error.
The public headline radar is concentrated in energy. That is the catalyst layer, not the trade instruction: the useful question is whether those stories confirm the board's mixed regime or merely create an opening burst that fades after liquidity arrives.
What to watch
Breadth confirmation0 bullish / 2 bearish; -1.5% mean five-session move
Defensive skew needs downside follow-through. A fast reversal above entry regimes would invalidate the premise before contractual risk is reached.
Volatility spread19.3% implied vs 11.7% realized
Watch whether implied volatility expands with price movement or collapses after the opening catalyst. That relationship decides whether direction alone is enough.
Leadership durabilityRepeat leaders: SPY
Recurring names deserve confirmation at the published entry, not looser terms. Repetition can signal durable leadership or a crowded thesis.
News catalyst1 ranked headlines across 1 themes
The leading energy headlines matter only where they alter cash-flow expectations, funding costs or volatility. Price confirmation decides whether the story belongs in the trade.
Risk budget$484 maximum one-lot basket loss (+$437 vs prior average)
Maximum losses are additive. Correlated names can fail together even when each spread is individually defined, so basket risk matters more than the comfort of any single cap.
Rolling comparison uses 5 retained published market sessions: Sep 28, 2026, Sep 24, 2026, Sep 22, 2026, Sep 21, 2026, Sep 18, 2026. The current screen ranked 22 candidates across 40 included symbols. Headline ranking uses publication time, market relevance, source quality, symbol relevance and topic diversity. Market evidence is timestamped Sep 28, 2026, 4:50 PM EDT. RFDELTA Top Option Trades is market intelligence, not individualized investment advice. Options can expire worthless, spreads can be assigned early, and displayed quotes may move before an order can be filled.
Why it ranks
The setup scores 100.00 on the common scale. Four-model consensus places probability of profit at 39.8%, 10.1% above the payoff hurdle, with 0.89 liquidity quality and positive modeled expectancy of $71.20.
IWM enters with -1.9% five-session momentum and -5.3% over twenty sessions. Realized volatility is 12.3%, placing the underlying in a risk off regime. The bearish structure expresses that tape without allowing the loss to expand beyond the spread debit or defined credit width.
Trade construction
Buy the 280 call and sell the 272 call, both expiring Oct 9, 2026. The credit mark of 5.63 assumes the long ask and short bid, not a midpoint. Do not accept less than 5.63 of credit without rerunning the payoff.
Maximum one-lot profit is $563.00, or 2.38 times maximum risk. The simulation assigns 20.8% probability to finishing near maximum profit and uses 20.6% implied volatility across deterministic jump-stress paths.